A Pensionable and Insurable Earnings Review, or PIER report, is one of those CRA notices that can make any employer’s stomach drop. It often shows up when there’s a mismatch in Canada Pension Plan (CPP) or Employment Insurance (EI) amounts reported on your employees’ T4s and T4 Summary.
The good news? Most PIERs are avoidable once you understand what triggers it and what to double-check throughout the year. This guide breaks down how a PIER works and the steps Canadian small businesses can take to prevent one.
What is a PIER report?
A PIER report is the CRA’s way of checking whether your CPP contributions or EI premiums match what you reported on year-end T4 statements. If something doesn’t add up, even by a small amount, the CRA may send a PIER report outlining:
- The names of the affected employees and the figures the CRA used in their calculations.
- A summary that shows any balance due.
- What you need to correct before penalties or interest apply
- A remittance voucher.
This isn’t just to make sure your small business is making the correct calculations. It’s also to make sure your employees or their beneficiaries receive:
- The correct CPP benefits when they retire, become disabled, or pass away.
- The correct EI benefits if they become unemployed, take maternity or parental leave or some other type of leave of absence.
Suggested Reading: Year-end payroll checklist for Canadian small businesses.
What triggers a PIER report?
Before we dive into the specific scenarios, it helps to understand why the CRA issues a PIER in the first place. A PIER is generated when the CRA detects a mismatch between what should have been deducted for CPP or EI and what was actually reported on your T4s and T4 Summary. With that in mind, here are the most common issues that trigger a PIER.
1. Taxable benefits not set up correctly
- If taxable benefits aren’t set up and taxed properly during your payroll processing, there can be calculation errors for EI and/or CPP contributions.
- Always double-check the if a benefit is taxable to confirm they’re set up right or use the CRA’s T4130 Employers’ Guide – Taxable Benefits and Allowances.
2. Changes to the number of pay periods or pay cheques
- In order to determine the amount of CPP contributions that come off each pay cheque, the CRA formula uses the number of pay periods (based on pay frequency) that the employee is expected to be paid. From there, the contribution is prorated and spread out on each pay cheque. That means that if there are any changes to the number of anticipated pay periods or the number of pay cheques the employee actually received that calendar year, there can be a CPP variance.
3. Off-cycle or manual pay runs
- While changing a pay frequency from biweekly to semi-monthly may be obvious, it can be easy to forget if you have issued a one-off (AKA off-cycle) pay cheque at some point during the year, such as a bonus or even retroactive pay. Any additional pay cheque outside of the set pay frequency can lead to an error in calculating CPP contributions.
4. Incorrect employee birthdates
- Pensionable earnings are only applicable if you’re between the ages of 18 and 70. If pensionable earnings are recorded outside that age bracket, the CPP contributions and pensionable earnings won’t match what CRA expects.
5. Year-to-date totals entered incorrectly
- Pay special attention when porting over or inputting year-to-date totals if you begin using a different payroll system or new software. If those starting numbers are entered incorrectly, it means the calculations moving forward will be off.
6. Errors in box 28
- Box 28 on the T4 shows whether an employee is exempt from CPP/QPP, EI, or PPIP (Quebec’s parental insurance plan). If the box doesn’t match what you actually deducted, CRA’s numbers won’t line up with the slip. As a result, you could get a PIER.
7. Incorrect SINs or names
- A small typo in a Social Insurance Number or name can also trigger a PIER. That’s because CRA can’t match the slip to the employee’s record. Before you file, check each SIN and legal name against the employee’s SIN confirmation letter and TD1. This is especially important for new hires and anyone whose name has changed.
If you aren’t using a payroll software like Wagepoint, here are some instructions from the CRA to manually calculate and verify your CPP and EI calculations:
How can you avoid a PIER report?
To prevent a PIER, it helps to understand how the CRA evaluates your payroll in the first place. Most discrepancies come from CPP pensionable earnings or EI insurable earnings that were calculated incorrectly. So before we get into prevention, let’s take a closer look at how CPP works and what counts as pensionable earnings.
CPP and pensionable earnings
Pensionable earnings are used to calculate the amount of CPP contributions due to the CRA. It’s important to remember that CPP contribution rates, maximums and exemptions are updated annually. As of 2024, there is a second additional CPP contribution (CPP2) rate and maximum that needs to be accounted for, in boxes 16A (or box 17A for QPP2 in Quebec).
Suggested Reading: A Small Business Guide to CPP2.
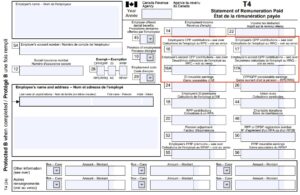
Pensionable earnings are recorded in box 26 on the T4 slip
CPP / QPP contributions are recorded in boxes 16, 16A, 17 and 17A on the T4 slip
If the pensionable earnings are incorrect, then the CPP contribution calculations will also be incorrect. Let’s review some tips to ensure your pensionable earnings are correct.
Determining what is pensionable
Generally speaking, if an amount is considered taxable income, it’s also pensionable income — meaning it’s subject to CPP contributions (when calculated in accordance with the Income Tax Act).
Common types of pensionable income
- Most taxable benefits and allowances count as pensionable
- Check out this handy CRA tool to determine if a benefit is taxable
- Regular earnings like wages, salary, commissions, and most forms of remuneration are pensionable
- Don’t forget tips and gratuities, the CRA offers a deeper dive on how to treat tips and gratuities here
- For those in Québec, please see Revenu Québec’s Québec Pension Plan (QPP) page for more information.
EI and insurable earnings
Similar to the pensionable earnings, making an error in insurable earnings will also result in incorrect EI premium calculations potentially earning you a PIER report. Insurable earnings also have EI premium rates and maximums that change annually, so be sure to keep up to date.
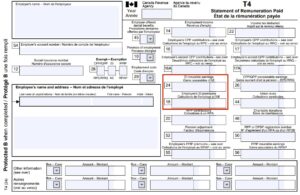
Insurable earnings are recorded in box 24 on the T4 slip.
EI premiums are recorded in box 18 on the T4 slip.
Determining insurable earnings
Before you can tell whether a payment needs EI premiums deducted, you first need to know how the CRA classifies it. Insurability depends on whether a benefit is cash, non-cash, or near-cash.
Cash
A benefit is cash when it’s paid in currency, by cheque, or by direct deposit. When a cash benefit is taxable, it’s also insurable, so you need to deduct EI premiums.
- Earnings: regular wages, overtime, vacation pay, and bonuses (special payments chart)
- Taxable benefits: cash gifts and awards (gifts and awards) and taxable allowances paid in cash (T4130)
- Edge case: if an employee is on a third-party wage-loss plan and you top up their pay, the top-up is generally subject to CPP but not EI (wage-loss replacement plans).
Non-Cash
A non-cash (or “in kind”) benefit is a good, service, or property you give an employee. Taxable non-cash benefits are generally not insurable, so don’t deduct EI premiums.
- Earnings: not applicable, since wages are always paid in cash.
- Taxable benefits: a bus pass, a parking space, or a gift card for a specific store (T4130, gifts and awards)
- Edge cases: CRA lists two exceptions that are insurable: board and lodging provided while the employee is also paid a cash salary, and employer-paid RRSP contributions the employee can withdraw (T4130).
Near-cash
A near-cash benefit works like cash or can easily be turned into cash. Like non-cash benefits, taxable near-cash benefits are generally not insurable.
- Earnings: not applicable.
- Taxable benefits: prepaid gift cards that can be used almost anywhere (e.g. prepaid Visa or Mastercard), plus shares, bonds, securities, and precious metals
- Edge case: a store gift card only counts as non-cash if it meets all of CRA’s conditions: it can only be used at that retailer (or a named group of retailers), it can’t be converted to cash, and you keep a log. If it misses any of these, it’s near-cash. Either way, it’s not insurable.
Keep in mind: a benefit can be taxable without being insurable. Check both before you set it up in payroll.
Suggested Reading: Taxable benefit mistakes you can’t afford to make.
What happens if you receive a PIER report?
A PIER isn’t a penalty, it’s a notification that something needs correcting. When a discrepancy is found, The CRA will send you a PIER report. If you’re registered for My Business Account (or Represent a Client, if you manage payroll for clients), you can also view, download, and reply to it online.
You agree with the CRA’s calculations
If you review the PIER and agree with the CRA’s calculations, you can simply pay the balance owing by the deadline. Once the payment is made, no further action or response is required.
You don’t agree with the CRA’s calculations
If you don’t agree with the discrepancies outlined in the PIER, you’ll need to respond to the CRA. Send any corrected information, supporting details, and a brief explanation of why your calculations differ.
When you receive a PIER, the CRA follows a set timeline. Here’s how it works:
- Day 1: The initial PIER package is sent and you have 30 calendar days to reply.
- Day 45: If you don’t reply or send a payment for the balance due, a notice of assessment will be sent.
- Day 65: The CRA will issue and send you amended T4 slips based on their assessment
What happens if you make a CPP or EI deduction mistake?
You deducted more CPP contributions or EI premiums from the employee (overpayment).
If you realize that you’ve mistakenly over-deducted CPP or over-deducted EI from an employee’s payroll, don’t worry. You can adjust it on the employee’s next cheque as long as it’s during the same calendar year as the earnings in question. Ensure the correction is reflected in both the employee and employer contribution amounts, and that everything is submitted accurately and on time with your source deductions to the CRA.
If you don’t catch the overpayment during the year that the earnings were paid in, employees will be refunded when they file their income tax and benefit returns. Employers can also apply for a refund of EI and CPP overpayments directly from the CRA by filling out Form PD24, Application for a Refund of Overdeducted CPP Contributions or EI Premiums.
You under-deducted CPP contributions or EI premiums from the employee (recovering)
If you under-deduct EI or CPP on an employee’s payroll, you can recover the employee’s contributions from later payments to the employee. The recovered contribution can be equal to, but not more than, the amount you should have deducted from each payment.
NOTE: You cannot adjust the employee’s income tax deduction to cover the CPP or EI shortfall.
How payroll software helps prevent PIER reports.
Payroll can be daunting. But when you keep these things in mind before your year-end review, you’re more likely to avoid a PIER report.
Closing out the year and staying compliant along the way gets a whole lot easier when you’re not doing it alone. With the right software, you don’t have to second-guess your calculations or scramble for updated tax tables. Wagepoint handles the math, keeps everything current and puts your employee forms and employer summaries right where you need them at year-end.
You stay focused on your team, and Wagepoint keeps the payroll worries off your plate. Learn more about Wagepoint or book a demo to see how we can support your small business throughout the year.